Foundation Repair Financing Options: 2026 Comparison Guide
Table of Contents
- Foundation Repair Financing Options in Littleton, Colorado: What Homeowners Need to Know
- How to Choose the Right Foundation Repair Financing Option
- HELOC vs Personal Loan for Foundation Repair
- Credit Score Needed for Foundation Repair Financing
- Homeowners Insurance and Government Grants for Structural Repairs
- Monthly Payment Plans and Contractor Financing Options
- Your Next Steps for Foundation Repair Financing in Littleton
Foundation Repair Financing Options in Littleton, Colorado: What Homeowners Need to Know
Exploring foundation repair financing options in Littleton helps homeowners address the significant investment that structural repairs often demand. We know that unexpected foundation issues can strain any budget, which is why our team at Rocky Mountain Steel Piering, Inc. provides a straightforward path: during your free initial consultation, we deliver a custom project quote that includes a detailed scope of work, documentation many lenders require for loan applications. Common financing tools like home equity lines of credit (HELOCs) offer revolving credit for phased repairs, while personal loans provide fixed-rate lump sums for projects with known total costs. Because every foundation repair job in Littleton presents unique challenges, our licensed inspectors tailor each estimate to the exact stabilization work your home needs. Starting with a clear, no-obligation estimate eliminates surprise cost barriers, and understanding which financing path suits your situation is the logical next step toward a secure, stable home.
How to Choose the Right Foundation Repair Financing Option
With several ways to pay for foundation repair available in Littleton, the right choice depends on your timeline, equity, and budget. Before applying for any loan, secure a detailed project scope and cost estimate from a qualified contractor—lenders typically require this documentation to approve financing.
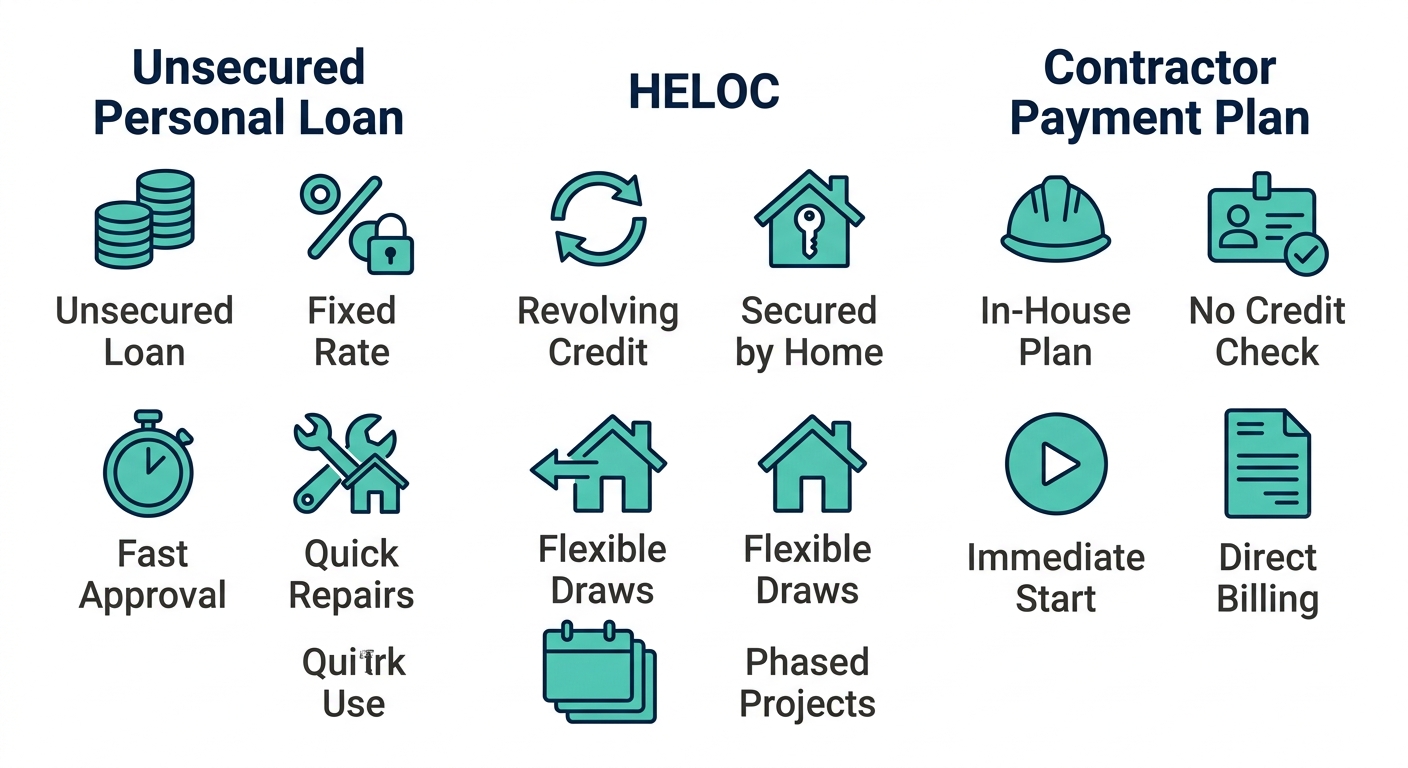
Unsecured personal loans offer a fast, fixed-amount option without home equity. They can fund within days, making them ideal for emergency repairs where the total cost is known. Approval depends on credit history and income, and rates may be higher than secured alternatives.
A Home Equity Line of Credit (HELOC) uses your home equity as collateral and provides a revolving credit line. This approach works well for multi-phase foundation projects because you draw funds as needed and pay interest only on the amount used. The approval process is slower—typically weeks—and requires a home appraisal, adding time to the initial timeline.
Some contractors offer in-house payment plans with no collateral and immediate availability upon agreement. These can help if your credit limits other options, though terms vary.
Government grants, though rare, may be available through state or local programs for emergency or qualifying low-income situations; expect multi-month application timelines.
| Method | Source | Collateral | Speed | Best For |
|---|---|---|---|---|
| Unsecured Personal Loan | Bank or credit union | None | Fast (a few days) | Quick repairs without equity |
| HELOC | Mortgage lender | Home equity | Slower (weeks) | Phased large projects |
Our team at Rocky Mountain Steel Piering, Inc., family-owned in Littleton since 1996 with an A+ BBB rating, has guided property owners through these decisions. We start with a free on-site inspection and a transparent, custom quote that defines the repair scope, exactly what lenders need to process your application.
For homeowners weighing two of the most common choices—HELOCs and personal loans—understanding their trade-offs is key to making a confident decision. Ready to start your construction project? Schedule your free inspection and financing consultation today to explore which method aligns with your foundation repair needs.
HELOC vs Personal Loan for Foundation Repair
Once you understand the factors to consider when reviewing foundation repair financing options, it becomes easier to evaluate the two main options homeowners consider: Home Equity Lines of Credit (HELOCs) and Personal Loans.
A HELOC provides a revolving line of credit secured by the equity in your home and, as such, provides a flexible source of funds to draw down as work progresses. Since foundation repair work, in some cases, may be done in multiple phases (like repairing drainage and concrete work), a HELOC for foundation repair in Littleton, allows you to borrow only what you need when you need it. In addition, a HELOC generally carries a lower interest rate than unsecured debt. Since the credit line is secured by your home equity, the lender will want to review your equity position and your credit, and may require an appraisal of your home to verify your equity position. Our team can help facilitate this process by providing a detailed project scope and a copy of your foundation repair contract.
A personal loan, on the other hand, provides a lump sum of money with a set repayment term, is generally unsecured (meaning it does not tie directly to your home equity), and may carry higher interest rates and stricter credit thresholds. A personal loan may, however, be a better option if you prefer the predictability of a fixed, monthly payment. Further, a personal loan may provide faster access to capital.
Balancing these two options depends on your project timeline, equity position, and personal preference for flexible versus fixed repayment. We simplify this decision by providing custom financing quotes for both HELOCs and personal loans during our free inspection and consultation. Rather than handing you a generic rate sheet, we assess your foundation’s condition and repair scope, then walk through how each loan product complements your specific situation. As a family-owned and operated company since 1996, we understand that every foundation project is unique, and our A+ BBB accreditation reflects our commitment to transparent, pressure-free guidance. Our team supplies the lender-ready project documentation that financial institutions require, so you can move forward with confidence. Credit score requirements and underwriting criteria will further influence which option is accessible to you.
Credit Score Needed for Foundation Repair Financing
While a personal loan offers a lump-sum cash payment and a HELOC provides secured, revolving credit, the option you can choose depends largely on your credit. Our complimentary on-site inspections help clients with this first step. As we assess your home’s foundation, we review lender credit expectations and provide a personalized financing proposal based on your project. Our company has served in this area since 1996.
Lenders evaluate credit differently for each product. HELOCs, being secured by your home, tend to require good credit—many lenders look for a history of on-time payments and a stronger credit score. Personal loans, on the other hand, may be available to those with fair credit, but the interest rate and terms adjust to reflect risk. The lower your score, the more you can expect to pay in interest, making it wise to pre-qualify without a hard credit pull before committing.
There are many factors lenders consider when making a decision, and your credit score is only one of them. Other factors may include your current debts and monthly income, your current employment and the stability of your income, and the amount of home equity you currently have, in the case of a HELOC. A thorough, professional estimate from a licensed contractor can strengthen an application. Our quotes provide sufficient detail to help financial institutions view the repair as a clear, limited investment, as opposed to a vague, unlimited expense.
Before you apply, we recommend pulling your credit report, correcting any errors, and using pre-qualification tools to see potential rates without affecting your score. Then schedule a no-obligation inspection at our Littleton, Colorado facility. During that visit, we walk through your credit situation and the financing paths available to you, so you can move forward with confidence. Once you understand what credit tier you fall into, you can also explore homeowners insurance coverage and government grant programs that may help offset structural repair costs.
Homeowners Insurance and Government Grants for Structural Repairs
Even with a well-managed credit history, the cost of structural repairs can create financial pressure, and it’s not uncommon for homeowners in Littleton and the Denver metro area to utilize a combination of personal financing, insurance and government programs to assist with those repairs. Knowing what is covered under your homeowners insurance and what grants may be available can make a significant difference in what you may need to finance.
Accident and loss damage coverage pays for unforeseen and unexpected losses and damage to a property from certain perils. If a covered event damages your home’s foundation, a claim may be approved. However, claims related to earth movement and gradual settling are typically excluded, as are pre-existing conditions. Damage caused by poor construction, tree roots, and expansive soil are usually not covered, either. Because policy terms differ, we recommend reviewing your plan with your insurance agent to confirm whether structural repairs fall under dwelling coverage. If a covered loss occurred, and a claim is justified, you may need a professional, no cost inspection and scope of repairs to substantiate the claim to your insurance company.
Colorado state and USDA programs can help, too, if you own a home, qualify for low-income status, and meet other eligibility requirements. The USDA’s Section 504 Rural Repair and Rehabilitation program offers grants to very-low-income seniors, ages 62 and older, to remedy health and safety hazards that may include foundation deficiencies. The FHA 203(k) loan combines the purchase or refinance of a home with the repair of major structural defects and improvements. Local housing authorities may administer local grants or forgivable loans. Contact your local agency to learn what is available to you. As with insurance and grants, many local programs require an assessment of your property and a detailed scope of the work by a licensed contractor.
Once insurance and grant funds have been exhausted, a gap often remains. At Rocky Mountain Steel Piering, our family-owned and A+, BBB-accredited company, can provide clarity with a free on-site assessment, detailed project scope, and cost estimate. These are essential to insurance adjusters and grant reviewers. If a gap still exists, we help explore alternative financing by explaining options including home equity lines of credit (HELOC) for phased projects, or personal loans for a fixed term and rate, based on the cost of the needed repairs. With insurance and grants fully explored, our financing can then bridge the final gap toward repairing your home’s structure.
Monthly Payment Plans and Contractor Financing Options
After looking at how insurance and government grants may help pay for structural repairs, we recognized that many homeowners would still face out-of-pocket expenses. For this reason, we offer several financing options that would make the cost of repairing your foundation’s stability manageable within your monthly budget.
Our process begins with a free, on-site inspection, and a presentation of financing options at that time tailored to the specific scope of work.
Home equity lines of credit (HELOCs) are secured by your home and provide revolving credit that you draw down as needed, and work well for projects that are funded in phases because they often carry variable rates that reflect current market conditions. For projects where you know the total cost, you may want to consider a personal loan that provides a lump sum with a fixed interest rate and monthly payment. The documentation we provide outlining the work to be done may also help you secure a loan with any lender.
Deferred-interest arrangements add another layer of flexibility. These plans typically carry a promotional period with no interest charges, after which standard rates apply to any remaining balance.
| Plan Type | Provider | Down Payment | Interest | Speed |
|---|---|---|---|---|
| In-House | Rocky Mountain Steel Piering | Custom, determined during consultation | Fixed or variable depending on plan | Immediate availability upon approval |
| Third-Party Lender | Partner lenders (details provided during consultation) | Varies by lender (typically 0–10%) | Fixed or variable market rates | Funding within 48–72 hours |
| Deferred-Interest | Third-party lenders or in-house promo | Often 0% down | 0% for a promotional period, then standard rate | Funding within a few days |
Given the information provided above, we help you determine the plan that works within your budget and repair schedule because each option offers distinct advantages and the right choice depends on factors like project timeline, total cost, and whether you prefer fixed payments or revolving credit.
We start the financing process with a free, no-obligation inspection described in the following section and guide you through securing the funding that fits your situation.
Your Next Steps for Foundation Repair Financing in Littleton
With a clear picture of the monthly payment plans and contractor financing options available for your foundation repair, the next step is to reach out to us for a free on-site inspection. During this obligation-free visit, we walk through your property’s specific needs and present personalized financing guidance that covers both HELOC and personal loan approaches tailored to your budget.
As a family-owned and operated business, serving the Littleton and Denver Metro area since 1996 with an A+ BBB accreditation, we integrate the financing conversation into the initial consultation so you leave the inspection with a preliminary written estimate and an understanding of which funding path fits your project. We also recommend consulting a licensed structural engineer or other qualified professional for a definitive diagnosis and design recommendations.
If you are interested in learning more about the financing options for foundation repair in Littleton, contact us to set up your free consultation.
Plan Your Foundation Repair Financing
You’ve examined the top financing routes for foundation repair—HELOCs, personal loans, contractor payment plans, and grants—and you’re ready to make a decision. We offer a free, no-obligation on-site inspection in Littleton, Colorado to review your foundation’s condition and recommend a custom financing plan. During the visit, our team will discuss which options suit your budget and timeline, not generic rate sheets. Backed by family ownership since 1996 and an A+ rating with the Better Business Bureau, we’ve helped countless local homeowners navigate the funding maze. You’ll receive a written estimate after the inspection, with no commitment required and no hidden surprises. Take advantage of our transparent process to secure the best funding for your structural repairs. Call +1 303-471-1155 or visit our website to schedule your free appointment today.